DSCR loans are having their biggest year yet. Bank of America projects non-QM lending, the category DSCR loans belong to, will reach about $175 billion in 2026, up from $108 billion in 2025. DSCR and other investor loans make up about half of it. But a boom brings closer scrutiny, and investors who close in 2026 are the ones who show up with a clean file.
DSCR lending is booming
A DSCR (debt service coverage ratio) loan qualifies you on the property’s rent, not your personal income. That makes it the go-to loan for self-employed investors and anyone growing a rental portfolio.
Demand has exploded. By some estimates, DSCR volume in private lending markets has nearly doubled from last year. Investors like that a DSCR loan doesn’t need tax returns, W-2s or a debt-to-income calculation.
Why lenders are getting stricter
More volume means more attention. Loans made in 2022 through 2024 have seen delinquencies creep up. Lenders responded by tightening their guidelines, and loans made in 2025 have performed better as a result.
Industry analysts are also watching how higher rates affect investor properties. With the 30-year average at 7.32% (Freddie Mac, October 22) and the Fed holding steady, a rental has to carry a bigger payment than it did a few years ago. Lenders want proof the rent really covers it.
What underwriters look at hardest
None of these are new rules. What’s changed is how closely each one gets checked, so documentation that was “good enough” two years ago may not be today.
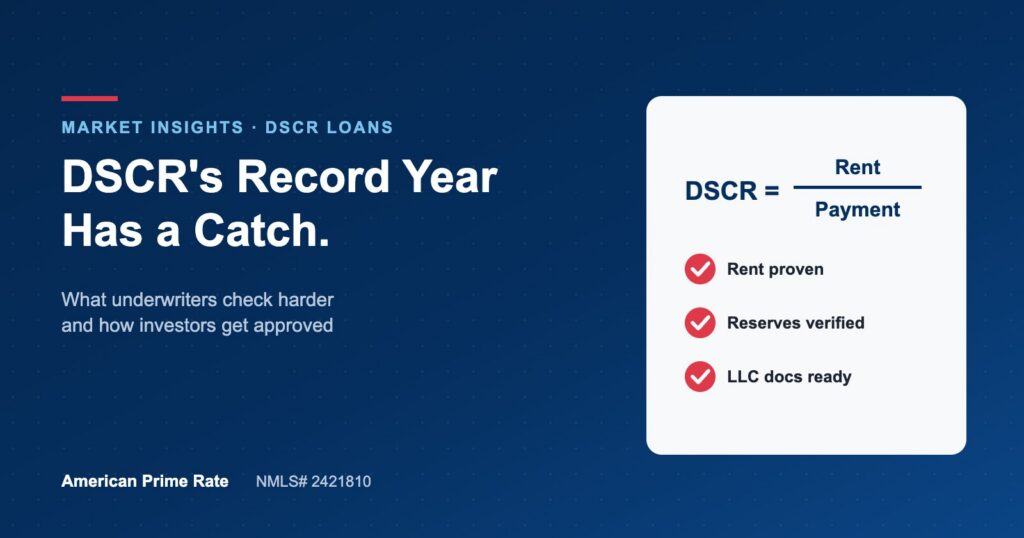
- Rent you can prove. Expect the appraiser to confirm market rent. If the property is leased, the lease should match what the tenant actually pays.
- Reserves and funds. Lenders want to see where your down payment came from and that you have months of payments in reserve after closing.
- Borrower and entity. Your credit history still matters, and if you’re buying in an LLC, the operating agreement and formation documents need to be ready.
Make the numbers work at 7%+
The ratio that drives every DSCR approval is simple:
If the ratio comes up short at today’s rates, you have levers: a larger down payment, an interest-only period, or a property with stronger rent for its price. We walked through each one in DSCR Loans at 7% Rates: How to Make a Rental Pencil This Fall.
Your pre-application checklist
- The lease, or a rent estimate for the property’s market.
- Two to three months of bank statements showing your down payment and reserves.
- LLC documents, if you’re closing in an entity.
- A list of properties you already own, if any, with their rents.
- Your target purchase price and closing date.
Have a rental in mind? Call (866) 569-2877 or learn about DSCR loans, and a licensed loan expert will tell you whether the deal works and how to structure it.
Market figures are published industry estimates and national averages as of the dates shown, not an offer of credit. DSCR loans are for business-purpose, non-owner-occupied investment properties. All loans are subject to underwriting approval and program guidelines. American Prime Rate LLC, NMLS# 2421810. Equal Housing Opportunity.