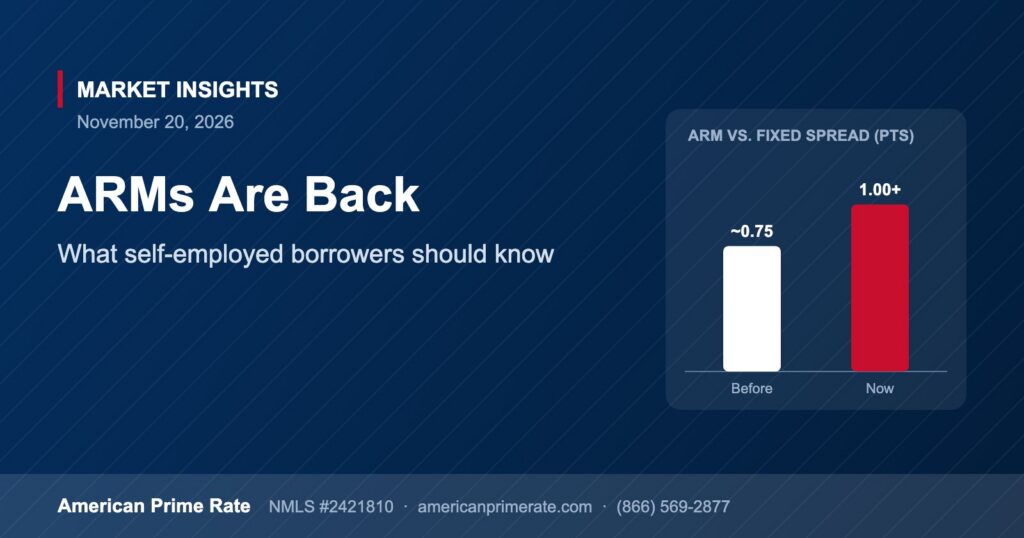
Adjustable-rate mortgages are making a comeback. The Mortgage Bankers Association said the ARM share of applications rose to 11.4% for the week ending Oct. 30, the highest reading since September 2025 (Mortgage Professional America). ICE’s November Mortgage Monitor found ARMs made up more than 10% of rate locks in early October, with the spread between a 5/1 ARM and a 30-year fixed widening from about 0.75 percentage point to more than 1 point (ICE).
For self-employed borrowers using non-QM loans, that trend raises a fair question: should you be looking at an ARM too? Here’s how to think about it.
Why ARMs are back
The reason is simple. With the 30-year fixed averaging 7.11% on Nov. 12, according to Freddie Mac, borrowers are looking for anything that lowers the starting payment. An ARM typically offers a lower initial rate for a fixed period, often five, seven or ten years, then adjusts based on a market index.
A wider gap between ARM and fixed rates makes the trade-off more tempting. But a lower starting rate also comes with uncertainty later.
How this applies to non-QM borrowers
Non-QM loans, including bank statement, P&L, 1099 and asset-based programs, are built for borrowers whose income doesn’t fit a standard tax-return review. Many non-QM programs offer both fixed and adjustable options, and some include interest-only periods.
Non-QM has grown fast. HousingWire cited Bank of America estimates that non-QM originations could reach $175 billion in 2026. More lenders in the space means more product choice, but also more variation in how each program is structured.
For self-employed borrowers, the fixed-versus-ARM question often comes down to how predictable your income is and how long you plan to keep the loan:
| If this sounds like you… | A fixed rate may fit | An ARM may be worth comparing |
|---|---|---|
| Income | Seasonal or uneven deposits | Steady or growing deposits |
| Time horizon | Plan to keep the loan 10+ years | Expect to sell or refinance within the fixed period |
| Budget | Need a payment that never changes | Can absorb a higher payment after adjustment |
| Rate outlook | Don’t want to bet on rates | Comfortable with rate risk and know the caps |
Questions to ask before choosing an ARM
If an adjustable rate is on the table, these are the details to get in writing:
- How long is the fixed period? A 5-year fixed period and a 10-year fixed period are very different bets.
- What index does it follow, and what’s the margin? Your future rate is generally the index plus the margin.
- What are the caps? Most ARMs limit how much the rate can rise at the first adjustment, at each later adjustment and over the life of the loan.
- What’s the worst-case payment? Ask your lender to show the payment at the maximum allowed rate. If that number would strain your budget, take it seriously.
- Is there a prepayment penalty? Some non-QM loans, especially on investment properties, have one. That affects your ability to refinance early.
Prepare your file for a stronger application
Whichever structure you choose, a clean file helps. For bank statement programs, lenders typically review 12 or 24 months of personal or business statements. Large unexplained deposits, transfers between accounts and NSF fees all get questions. Clean those up now, and keep a short explanation ready for anything unusual.
It also helps to know how your business income has trended. Lenders often look for stable or rising deposits. A strong fourth quarter can help. If you may want a conventional loan later, it’s also worth asking your tax professional how write-offs affect the income lenders see on your return.
The bottom line
An ARM isn’t right or wrong on its own. It’s a tool that can make sense when you expect to sell, refinance or see your income grow before the fixed period ends, and you can handle the payment if rates are higher at adjustment. It can be risky if you’re counting on rates falling to make the numbers work.
If you’re self-employed and want to compare fixed and adjustable non-QM options side by side, explore non-QM loan programs or call American Prime Rate at (866) 569-2877. We’ll walk you through the trade-offs using your actual income documents.
Sources
- Mortgage Professional America, MBA Weekly Applications Survey, week ending Oct. 30 (Nov. 4, 2026)
- ICE Mortgage Monitor, November 2026 (Nov. 9, 2026)
- Freddie Mac Primary Mortgage Market Survey, Nov. 12, 2026
- HousingWire, “DSCR loans are booming amid fragmented underwriting standards,” Sept. 12, 2026
American Prime Rate LLC · NMLS #2421810. This is not a commitment to lend. All loans are subject to credit approval, appraisal and underwriting. Figures are market averages from the sources above, not rate quotes or offers. Examples are illustrative only.